




A home loan lets you buy a home now and pay for it over time. You pay a down payment, usually 10 to 25% of the property value. The bank lends the rest and holds the property as security. You repay the loan in fixed monthly installments called EMIs, often over 15 to 30 years.
For a first-time buyer, the process has five main stages:
- Check your eligibility. Income, credit score, and age decide how much you can borrow.
- Apply with your identity, income, and property documents.
- Get the sanction letter, which sets your loan amount, rate, and tenure.
- Let the bank verify the property, both legally and on-site.
- Sign the loan agreement and receive the money.
Buying your first home is exciting. The loan side often feels confusing, full of bank terms nobody explains.
This guide shows how home loans work for first-time buyers, in plain words. It covers how much you can borrow and how your EMI works. It also lists the documents you need and each step of the process. It also covers the costs and mistakes most first-timers only learn about later.
What Is a Home Loan?
A home loan is money a bank or housing finance company lends you to buy a house, flat, or villa.
The property itself is the security. Until the loan is fully repaid, the lender holds a legal claim on it. Once you pay the last EMI, the claim is removed and the property is fully yours.
You do not need to have the whole amount saved. You need the down payment, the purchase costs, and a steady income that can cover the EMI.
For most first-time home buyers in India, a home loan is the only practical way to buy property. It is also one of the cheapest forms of borrowing, because the loan is backed by a real asset.
Key Home Loan Terms, Explained Simply
Banks use a lot of terms. These are the ones every first-time buyer should know.
How Much Can You Borrow?
Two limits decide this. The bank applies whichever one is lower.
Limit 1: The Property Value (Loan-to-Value)
Indian banks cannot lend the full value of a home. The Reserve Bank of India caps the loan as a share of the property value:
The rest is your down payment. For most villas and larger apartments, plan on paying at least 20 to 25% yourself.
Stamp duty, registration, and furnishing are usually not counted in the loan. You pay those from your own savings, on top of the down payment.
Limit 2: Your Income (EMI-to-Income)
Lenders want your total EMIs to stay within a safe share of your monthly income. Most keep it around 40 to 50% of your take-home pay.
This includes every loan you already have: car loans, personal loans, and credit card EMIs. An existing car loan directly reduces how much home loan you can get.
Home Loan Eligibility: What Lenders Check
Home loan eligibility comes down to five things.
Income. A steady, provable income matters most. Salaried applicants show salary slips. Self-employed applicants show tax returns and business accounts.
Credit score. Most lenders prefer a score of 750 or above. A higher score can also get you a lower interest rate. A low score can mean rejection or a higher rate.
Age. Most lenders want the loan repaid by around 60 to 70 years of age. The older you are when you apply, the shorter your maximum tenure.
Job stability. Lenders like at least two years of work history and some time with your current employer. For the self-employed, they usually want two to three years of business records.
Existing debt. Fewer existing EMIs mean more room for a home loan.
Ways to Improve Your Eligibility
- Add a co-applicant. A spouse or parent with their own income raises the amount you can borrow.
- Choose a longer tenure. This lowers the EMI, so a larger loan fits your income.
- Close small loans first. Clearing a car loan or card balance frees up room.
- Check your credit report early. Fix any errors before you apply.
How Your EMI Works
Your EMI stays the same each month on a fixed rate. On a floating rate, it can change when rates move.
What changes over time is the split inside the EMI. Early on, most of each EMI pays interest. Later, most of it pays down the principal.
On a 20-year loan at 8.5%, around 80% of your very first EMI goes to interest. This is why paying extra in the early years saves the most money.
Tenure: Lower EMI, Higher Total Cost
A longer tenure lowers your monthly EMI. But you pay interest for more years, so the total cost rises sharply.
This table shows the effect at an illustrative interest rate of 8.5%:
Going from 20 years to 30 years cuts your EMI only a little. But it adds about 70% of the loan amount in extra interest.
The takeaway: choose the shortest tenure your income can comfortably handle. Prepay whenever you can.
Fixed Rate or Floating Rate?
Floating rate. Most home loans in India use a floating rate. It is linked to an outside benchmark, usually the RBI repo rate. When the repo rate falls, your rate falls. When it rises, your rate rises.
Fixed rate. The rate stays the same for a set period or the full term. You know your EMI exactly. Fixed rates usually start higher than floating rates.
For most first-time buyers, a floating rate makes sense. It is usually cheaper, and RBI rules let individual borrowers prepay floating-rate home loans without a penalty. Fixed-rate loans can carry prepayment charges, so check the terms.
Documents Required for a Home Loan
Have these ready before you apply. Missing documents are the most common cause of delay.
Identity and Address Proof
- PAN card (required)
- Aadhaar card
- Passport, voter ID, or driving licence
- Recent passport-size photographs
Income Proof: Salaried
- Salary slips for the last 3 months
- Form 16 for the last 2 years
- Bank statements for the last 6 months, showing salary credits
- Employment letter or ID
Income Proof: Self-Employed
- Income tax returns for the last 2 to 3 years
- Profit and loss statement and balance sheet, often audited
- Business registration proof (GST, shop licence, or partnership deed)
- Bank statements for the last 12 months
Property Documents
- Agreement for sale or allotment letter
- Title documents and the past chain of ownership
- Approved building plan
- RERA registration details, for a new project
- Occupancy Certificate, for a ready home
- Receipts for any payments already made to the seller
Goa-Specific Property Documents
Lenders in Goa will also ask for papers that are specific to the state:
- Form I and XIV, the land record showing the owner and land use
- Conversion Sanad, proving the land was approved for residential use
- Construction licence from the Panchayat or Municipal Council
- CRZ clearance, if the property is near the sea, a river, or a creek
Banks generally will not lend on agricultural land or on property built without approvals.
The Home Loan Process: Step-by-Step Guide
Here is the full home loan process from start to finish, with typical timelines. Timelines vary by lender and by how complete your documents are.
Step 1: Check Your Eligibility (1 day)
Use a lender's online eligibility calculator. Enter your income, existing EMIs, and age. This tells you roughly how much you can borrow before you start looking at homes.
Step 2: Get Pre-Approved (Optional, 3 to 7 days)
A pre-approved loan is a conditional approval based on your income and credit. It is not tied to a specific property yet.
It tells you your real budget. It also shows sellers you are a serious buyer. And it speeds up the final loan once you pick a home.
Step 3: Choose Your Property
Pick a home that fits your budget and that a bank will finance. Ask the seller or developer which banks have already approved the project. An approved project usually means a faster loan, because the bank has already checked the land and permissions.
Step 4: Apply and Submit Documents (1 to 2 days)
Fill in the application and submit your documents. You will also pay the processing fee at this stage. It is usually a small percentage of the loan, often up to about 1%.
Step 5: Credit Assessment (3 to 7 days)
The lender checks your credit report, income, job, and existing loans. They may call your employer or visit your home or office.
Step 6: Sanction Letter
If you pass, the lender issues a sanction letter. It states your approved loan amount, interest rate, tenure, EMI, and any conditions.
Read it closely. A sanction letter is usually valid for a few months. If you do not complete the purchase in that time, you may need to apply again.
Step 7: Legal and Technical Check of the Property (7 to 15 days)
This is the step first-time buyers do not expect. The bank checks the property, not just you.
The legal check: the bank's lawyer reviews the title, the ownership chain, and the approvals. In Goa, this includes Form I and XIV and the Conversion Sanad.
The technical check: A valuer visits the site. They confirm the property matches the approved plan and estimate its market value. The bank lends on the lower of the agreed price and this valuation.
This check also protects you. If the bank's lawyer finds a title problem, you learn about it before you pay the full price.
Step 8: Sign the Loan Agreement
Once the property clears, you sign the loan agreement. You hand over the original property documents, which the lender keeps until the loan is repaid.
Read the agreement before you sign. Check the rate, the reset terms, the prepayment rules, and all fees.
Step 9: Disbursement
The lender pays the loan amount, usually straight to the seller or developer, not to you. Your EMI or pre-EMI starts from the following month.
Typical total time: two to four weeks once your documents are complete. Projects already approved by the bank are often faster.
Ready-to-Move vs Under-Construction: How the Loan Differs
Whether your home is finished or still being built changes how the loan works.
Ready-to-Move Home
The bank releases the full loan at once, at registration. Your full EMI starts the next month.
There is no waiting and no construction risk. There is also no GST on a ready home once the Occupancy Certificate is issued.
Read More: Ready-to-move or Under-construction Property in Goa
Under-Construction Home
The bank releases the loan in stages, linked to construction progress. This is called tranche disbursement. Each release follows a stage such as the plinth, the slabs, and the finishing.
This fits neatly with a construction-linked payment plan, where you pay the developer at the same milestones.
Pre-EMI vs Full EMI
On an under-construction home, you have two ways to repay while it is being built:
Pre-EMI feels easier on your monthly budget. But your loan does not reduce at all while you pay it. If construction is delayed, pre-EMI lasts longer and you pay more interest for nothing.
This is why the developer's delivery record matters so much on an under-construction purchase.
Under RERA, a developer cannot take more than 10% of the price before a registered agreement for sale is signed. This protects your down payment in the early stage.
Read More: Buying an under-construction property in Goa
The Full Cost of a Home Loan
Your EMI is not the only cost. Budget for all of these.
Ask every lender for a full fee list in writing before you choose one. The cheapest interest rate is not always the cheapest loan once fees are added.
Paying Off Your Loan Early
Prepaying is the simplest way to save on a home loan.
Part-prepayment. Pay a lump sum, such as a bonus, toward the principal. You can then lower your EMI or shorten your tenure. Shortening the tenure saves more interest.
Foreclosure. Pay off the whole loan before the term ends.
No penalty on floating rates. RBI rules do not allow lenders to charge individuals a penalty for prepaying a floating-rate home loan. Fixed-rate loans can still carry charges.
Balance transfer. If another lender offers a clearly lower rate, you can move your loan to them. Count the new fees before you switch.
Tax Benefits on a Home Loan
A home loan can lower your income tax. Under the old tax regime, you can claim deductions on both the principal repaid and the interest paid. Joint owners who are also co-borrowers can each claim their own share.
The rules differ between the old and new tax regimes. They also differ for a home you live in and a home you rent out.
Our full guide explains the tax benefits on a home loan in detail. Confirm the current rules with a chartered accountant.
Joint Home Loans
A joint home loan has two or more borrowers, usually spouses or a parent and child.
Higher eligibility. Both incomes count, so you can borrow more.
Shared tax benefits. If both are co-owners and co-borrowers, both can claim tax deductions.
Shared responsibility. Every co-borrower is fully responsible for the loan. If one stops paying, the other must cover it. A missed payment also hurts both credit scores.
Some lenders offer a slightly lower rate when a woman is a co-owner or the main applicant. Ask your lender.
Home Loans for NRIs and Second Homes
NRIs can take home loans from Indian banks to buy property in India, including Goa. EMIs are paid through NRE or NRO accounts, and the documents differ. See our full guide to taking a home loan as an NRI.
A second home can also be financed. Lenders look more closely at your income, since you will be paying two loans or a loan plus rent. The tax treatment also differs. If you are buying mainly for rental income, read about taking a loan to invest in property.
Mistakes First-Time Buyers Make
Choosing the longest tenure by default. It looks affordable each month and costs far more overall.
Ignoring the full cost. Stamp duty, registration, fees, and furnishing are not in the loan. Many first-time buyers run short at registration.
Not checking the credit report first. An error you could have fixed can cost you a better rate.
Taking new loans just before applying. A new car loan cuts your home loan eligibility.
Comparing only interest rates. Compare fees, rate reset terms, and prepayment rules too.
Stretching to the maximum EMI. Just because a bank will lend it does not mean you should borrow it. Leave room for emergencies.
Picking a property the bank will not finance. Unapproved projects, agricultural land, or missing papers can stop a loan late in the process.
Skipping the agreement. Read the sanction letter and loan agreement in full before signing.
Getting a Home Loan in Goa
Getting a home loan in Goa works much the same as anywhere in India. Most major banks and housing finance companies lend here.
The difference is the property paperwork. Lenders will check Form I and XIV, the Conversion Sanad, and building approvals. They will also ask for CRZ clearance where it applies.
The type of project you choose affects how your loan runs.
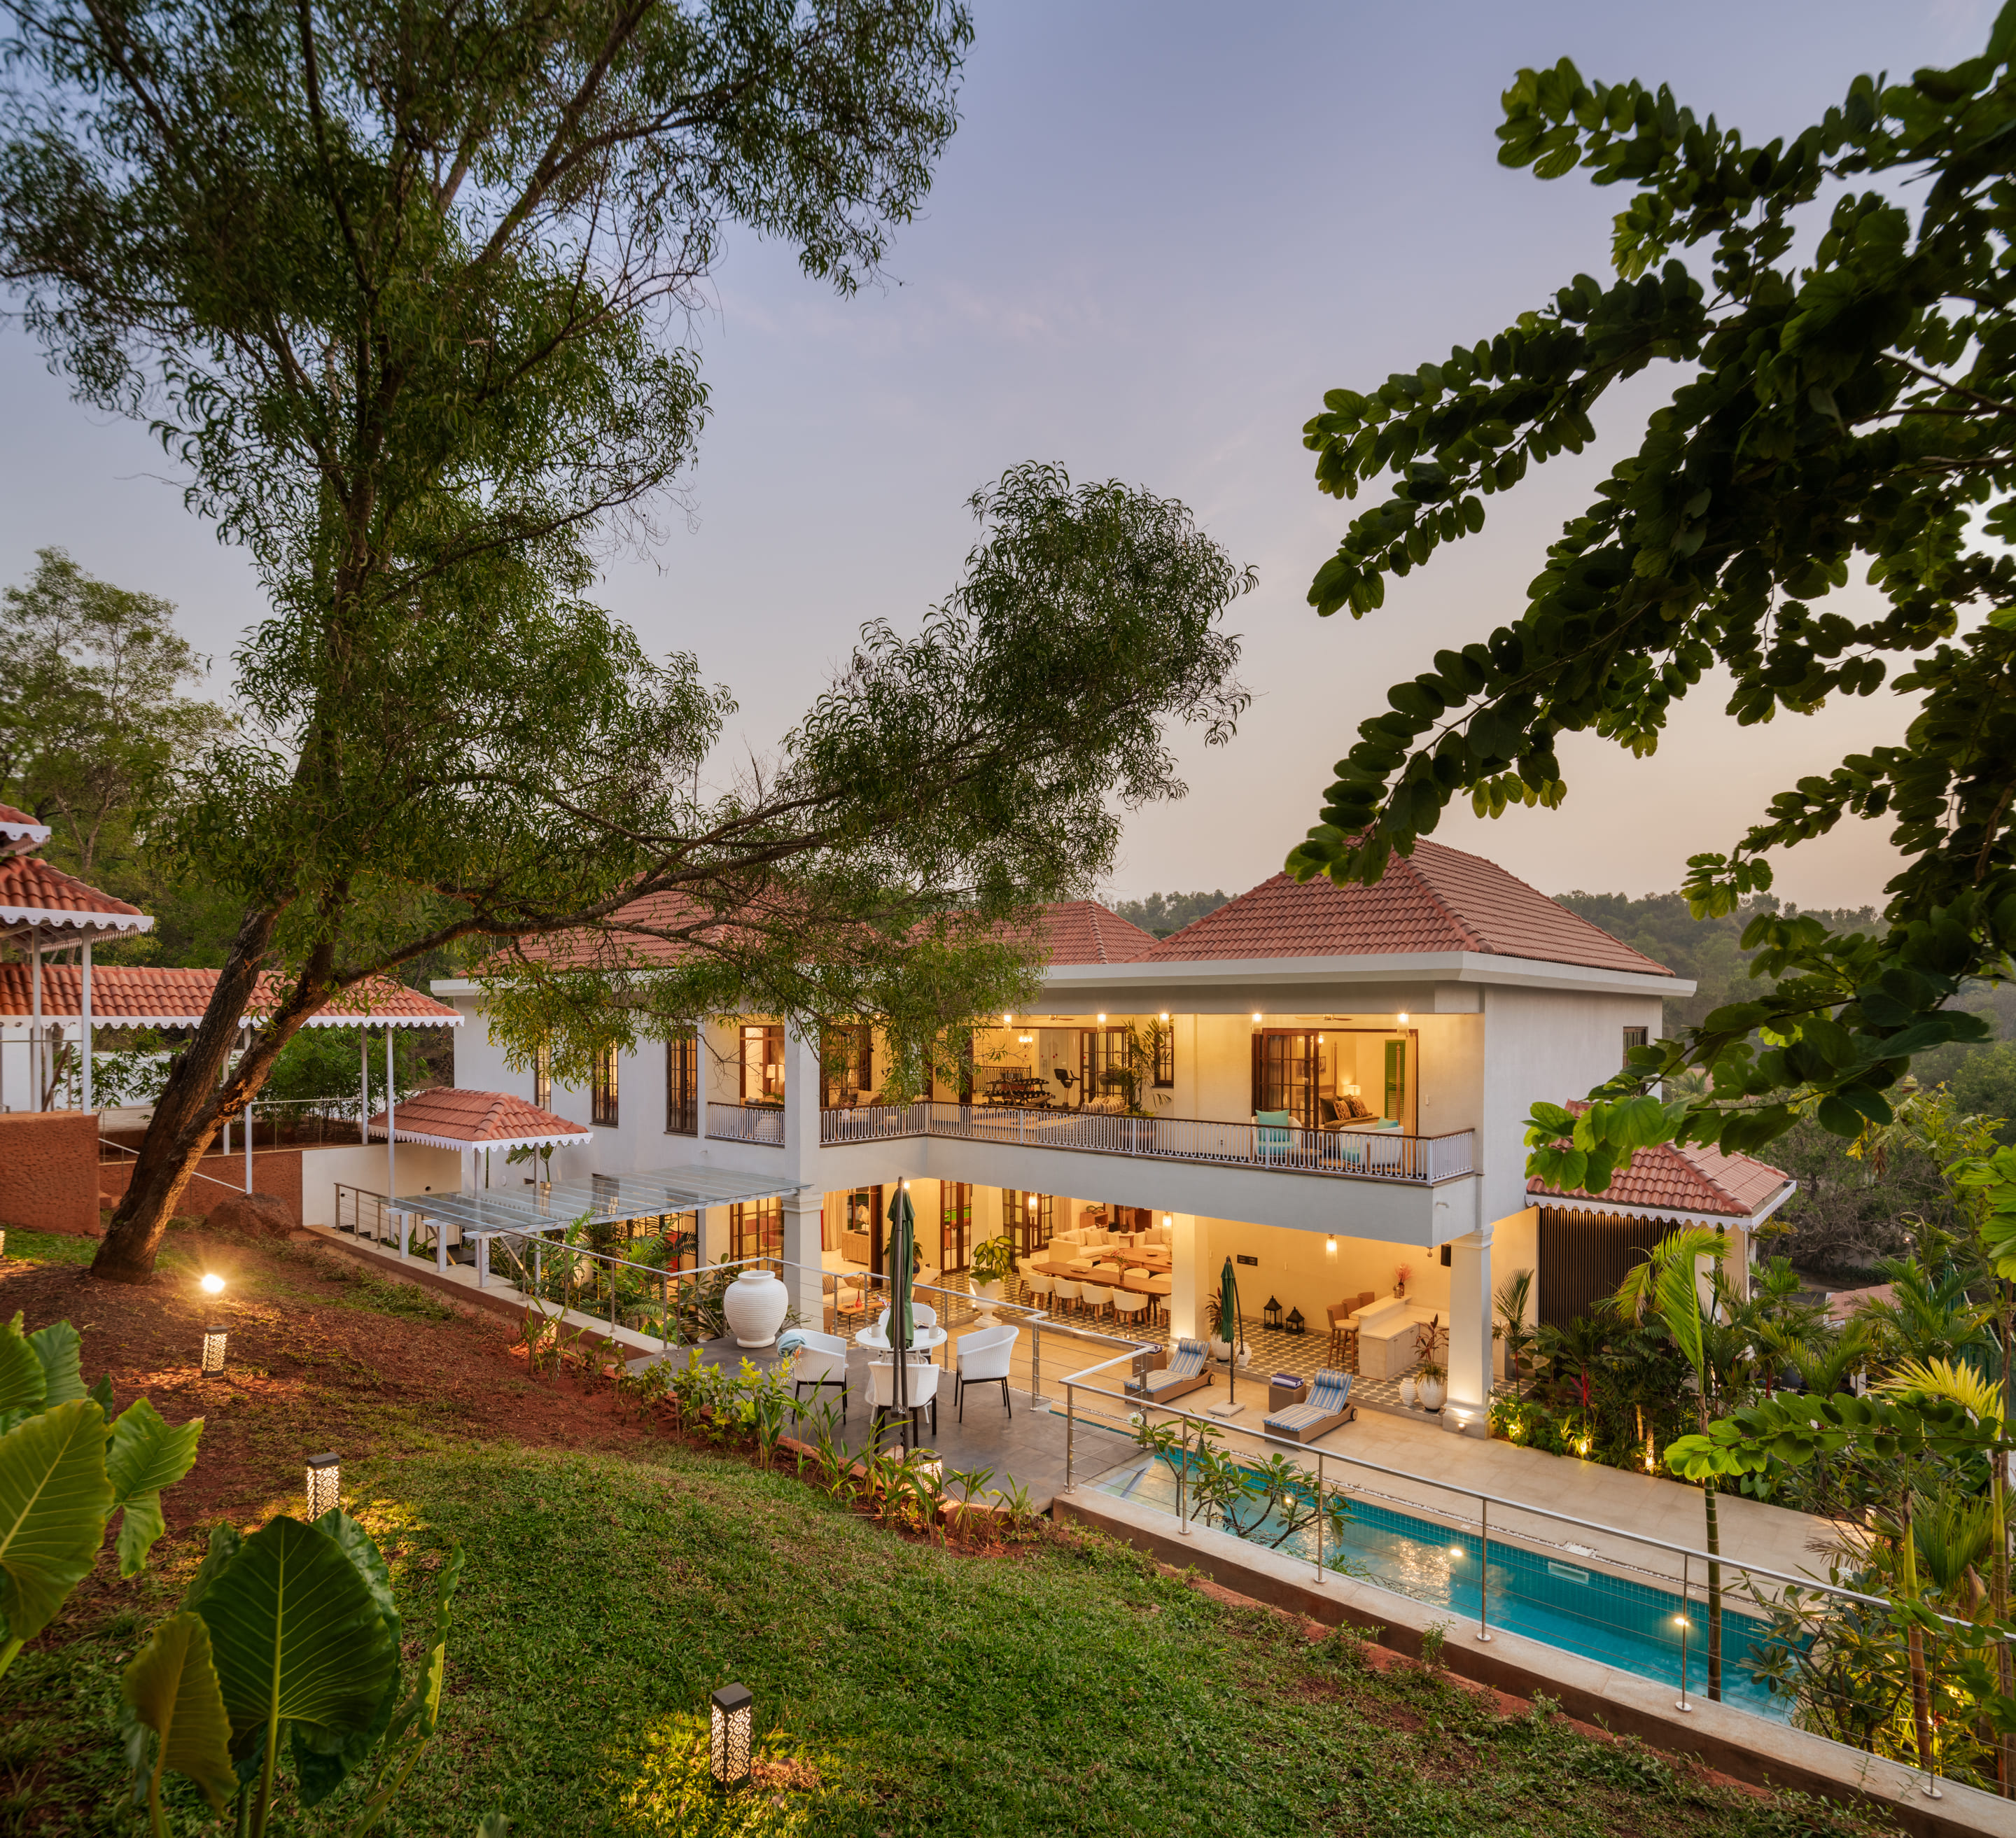
A ready-to-move home means the full loan is released at once and your EMI starts straight away. With no construction period, there is no pre-EMI. At Ashray Developers, Serenity in Anjuna is a ready-to-move villa project, and Daffodille in Pilerne offers ready-to-move furnished apartments.
An under-construction home suits a staged loan. At Chrysalis Phase 1 in Nerul, payments follow a construction-linked plan. You pay a small amount on booking and more on the agreement. The rest is paid at each building stage, which matches how a bank releases a home loan in tranches.
Whichever you consider, ask which banks have approved the project before you apply. New to the market? Our checklist for first-time property buyers in Goa covers the full purchase. Our guide to buying an apartment in Goa covers flats in detail.
Conclusion
Once you see how home loans work, first-time buyers usually find them simpler than expected. You pay a down payment, the bank lends the rest against the property, and you repay it in monthly EMIs.
Three things matter most with your first home loan. Know your real eligibility before you shop. Budget for the full cost, not just the EMI. And choose the shortest tenure you can comfortably afford, then prepay whenever you can.
Get your documents ready early and read every letter before you sign. Then buy a property the bank can finance without trouble. Do that, and your first home loan will work for you, not against you.
Ready to start looking? Browse our properties for sale across North Goa. Or talk to the Ashray team about ready-to-move and under-construction homes.
This guide is general information, not financial advice. Loan terms, rates, and tax rules change. Confirm the details with your lender and a qualified financial advisor or chartered accountant before you borrow.
FAQs
1. How does a home loan work for first-time buyers?
You pay a down payment, usually 10 to 25% of the property value. A bank lends the rest and holds the property as security. You repay the loan in fixed monthly EMIs over 15 to 30 years. Once the last EMI is paid, the bank's claim is removed and the home is fully yours.
2. How much home loan can I get?
Two limits apply, and the lower one wins. The bank can lend up to 75 to 90% of the property value, depending on loan size. Your total EMIs must also stay within about 40 to 50% of your take-home income. Adding a co-applicant or choosing a longer tenure can raise the amount.
3. What credit score do I need for a home loan?
Most lenders prefer a credit score of 750 or above. A higher score can also bring a lower interest rate. A lower score does not always mean rejection, but it can mean a higher rate or a smaller loan. Check your credit report and fix any errors before you apply.
4. What documents are required for a home loan?
You need PAN and identity proof, address proof, and photographs. Salaried applicants add 3 months of salary slips, 2 years of Form 16, and 6 months of bank statements. Self-employed applicants add 2 to 3 years of tax returns and business accounts. You also need the property's title, approved plan, and sale agreement.
5. How long does it take to get a home loan?
Usually two to four weeks once your documents are complete. Credit assessment takes about 3 to 7 days. The property's legal and technical check takes about 7 to 15 days. Projects already approved by the bank are often faster. Missing documents are the most common cause of delay.
6. What is the difference between pre-EMI and full EMI?
On an under-construction home, pre-EMI means paying only interest on the amount released so far. The loan itself does not reduce. Full EMI means paying principal and interest from the start. Pre-EMI is easier on your monthly budget, but full EMI costs less in total interest over the loan.
7. Can I repay my home loan early?
Yes. You can make part prepayments or close the loan fully. RBI rules do not allow lenders to charge individuals a penalty for prepaying a floating-rate home loan. Fixed-rate loans may carry charges. Prepaying early in the loan saves the most interest.
8. Should first-time buyers choose a fixed or floating rate?
Most first-time buyers choose a floating rate. It is usually lower at the start and can be prepaid without a penalty. A fixed rate gives a predictable EMI but usually starts higher and may carry prepayment charges. Compare both offers and their full terms before deciding.